
Crane Financing in Canada
Mobile cranes, crawlers, tower sections and boom trucks are among the heaviest purchases a lifting or construction business makes. Paying for one outright draws on the same account as payroll, fuel and mobilization.
Crane financing turns that purchase into fixed monthly payments on new and used machines alike, through a crane loan or a lease. Fincap has access to more than 30 Canadian lenders, and most requests come back with options within 24 to 48 hours.


Financing Solutions for Crane and Lifting Businesses
A lifting operation often needs more than one product: the crane itself, the cash to move it, and a way to bridge the invoices a general contractor has yet to pay.
- Equipment leasing covers the crane, with the payment set against the work it is booked on.
- Equipment refinancing draws capital back out of a machine you already own outright.
- Working capital loans carry operators, fuel and lowbed moves while progress draws are pending.
- Factoring advances invoices already issued to a general contractor.
Our heavy equipment leasing guide sets out how each structure works.
What Crane Equipment Can You Finance?
Whole machines and the gear that goes with them are eligible, new or used:
- Mobile and all-terrain cranes
- Rough-terrain and carry-deck cranes
- Lattice-boom and telescopic-boom crawler cranes
- Boom trucks and truck-mounted cranes
- Tower cranes and self-erecting tower cranes
- Overhead, bridge and gantry cranes
- Jib cranes and hoists
- Rigging and lifting accessories
- Counterweights, outrigger pads and transport trailers
- Load moment indicators and crane control systems
Equipment outside this list is usually eligible too, and the sectors we cover appear on the eligible equipment page.
Compactors, loaders and the rest of a mixed fleet fall under construction equipment financing.
Financing by Type of Crane Operation
- Crane rental and lifting service companies
- General contractors and construction firms
- Excavation and demolition contractors
- Industrial plants and warehouses running overhead cranes
- Owner-operators running a boom truck
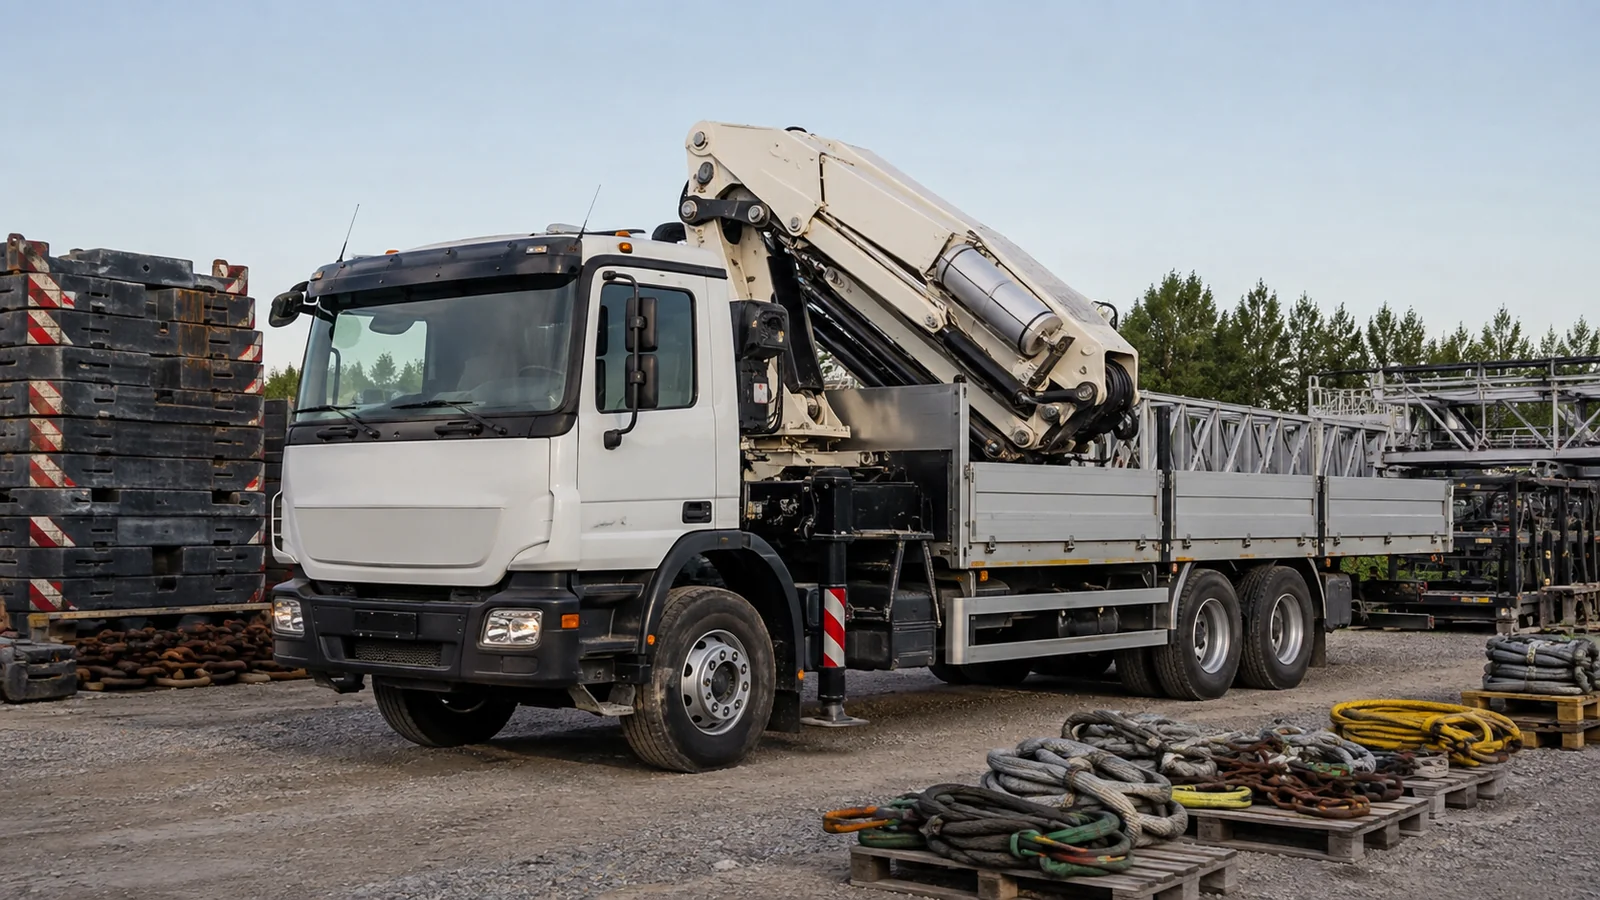
A boom truck is a road-registered chassis with a crane mounted on it. Crane truck financing covers both on a single request, even when the truck and the crane come on separate quotes.
New vs Used Crane Financing
A used crane is financed through the same process as a new one.
1. Financing a Used Crane
Lenders weigh the year, the hours on the meter, the boom and the ropes, and the resale value. No fixed age cap applies across the network, so condition and resale value carry more weight than the year on the plate. Well-maintained cranes hold their resale value, and the supply of good used units has tightened over the past two years. Used crane financing is reviewed faster when service records and a recent inspection report come with the application.
2. Buying at Auction or from a Private Seller
An auction listing or a bill of sale backs an application as well as a dealer invoice does. Machines bought at auction, from a fleet being wound down, or through a private sale are funded the same way. Talk to a broker before the sale closes: knowing the crane and the price in advance gives us time to line up a lender while the auction runs.
Why Choose Fincap for Crane Financing?
Going through a broker means your file goes to the lenders whose criteria it actually fits.
- Access to over 30 lenders across Canada means a file that misses one lender's criteria goes to another where it fits.
- Any make qualifies, new or used, bought from a dealer, at auction or privately.
- Sales tax is carried by the lender at purchase and spread across the term.
- A lease keeps the asset out of your debt position, which leaves your bank borrowing room free for the next project.
- Newly formed companies and operators with past credit trouble are reviewed rather than screened out. Clients rate the service 4.9 out of 5 across 122 Google reviews.
Who Qualifies for Crane Financing?
Approval turns on the whole operation, not on one credit score.
| Criteria | Details |
|---|---|
| Business type | Active Canadian company |
| Time in operation | Startups and established operators both reviewed |
| Credit history | A range of profiles accepted, including past credit difficulties |
| Down payment | Low or none on most files |
| Equipment | New or used, any make, dealer, auction or private sale |
| Coverage | Every province and territory |
What each lender weighs, and how to present it, sits in our guide to what lenders look for in an application.
Documents Needed for Your Application
Most of a crane file is paperwork you already have.
- The Fincap credit application
- Incorporation or business registration papers
- The dealer quote, auction listing or bill of sale
- Three months of business bank statements
- Financial statements on requests above $150,000
Send what you have rather than waiting on the last document, and we will ask for anything missing while the review runs.
How Crane Financing Works
Five steps take you from the crane you have found to funds in the seller's hands.
| Step | What happens | Timeline |
|---|---|---|
| 1. Choose your crane | Any dealer, auction house or private seller | Before applying |
| 2. Submit your application | The online form, with the quote attached | About 5 minutes |
| 3. Review your options | We bring back the structures your file qualifies for | 24 to 48 hours |
| 4. Select your terms | Pick the payment schedule that fits your contracts | Same day |
| 5. Get funded | Funds are released to the seller | On approval |
Typical Crane Financing Terms
| Element | Details |
|---|---|
| Amount | $10,000 to $5,000,000 and up |
| Term | 24 to 84 months |
| Rates | Competitive, based on your credit profile |
| Payment structure | Fixed, seasonal or deferred |
| Equipment condition | New and used both accepted |
| Extras covered | Freight, rigging and attachments on the same quote |
Ownership at the end of the term is where the two structures part ways. Crane leasing keeps the payments on the expense side and the asset out of your debt position. Each instalment on a crane loan builds equity, which suits a unit you mean to run for its full service life. Our article on negotiating lease terms covers what is open to discussion.
Growing Your Crane Fleet or Refinancing What You Own
Two situations bring operators to a broker: a contract you cannot take on without one more crane, and a yard of paid-off units tying up cash you could use.
1. Adding a Crane for a New Contract
A signed contract is the strongest document a new company can bring, because it shows how the monthly payment will be covered. Without an operating history, the review rests on that contract, the crane and your own background. Several lenders we work with fund newly formed companies, and our article on leasing for startups sets out what they ask for.
2. Refinancing an Owned Crane to Free Up Cash
A crane you own free and clear secures a new advance: for a deposit, for working capital through a slow quarter, or for mobilization on work already signed. Past credit trouble does not rule out the request: our article on refinancing with bad credit covers how those files are read.
Crane Financing Across Canada
Crane equipment financing is arranged in every province and territory, and nothing in the process calls for a meeting: application, review and funding run remotely. Pages exist for the markets we see most:
- Equipment Financing in Ontario
- Equipment Financing in Calgary
- Equipment Financing in Edmonton
- Equipment Financing in Vancouver
- Equipment Financing in Winnipeg
- Equipment Financing in Saskatchewan
For Crane Dealers and Distributors
Presenting terms at the moment of sale removes the delay between your quote and the order.
Our vendor program adds that option to your sales proposal, with the credit review handled by our representatives and credit analysts, not your sales staff.
FAQ About Crane Financing
For anything the answers below do not cover, call 819-643-9997 or reach us through the contact form.
1. What credit score do I need to finance a crane?
No minimum is published, and no single score decides a file. A lender looks at your years in operation, the contracts you have signed, the unit itself and the cash flow behind it. Files a bank declined on score alone are frequently placed elsewhere.
2. Can I finance a used crane, and is there an age limit?
Yes, and age is not a cutoff on its own. What shifts with age are the term and the deposit a lender offers. An inspection report may also be requested.
3. Crane leasing or a crane loan: which structure fits?
It comes down to how long the crane stays in your fleet and what you want carried on your books. Our brokers run both against your own numbers, and our comparison of buying and leasing sets out the trade-offs.
4. Can I get boom truck financing for a single unit?
Yes. Boom truck financing on a single truck-mounted unit follows the same route as a fleet order. Owner-operators are a standard profile, and the chassis and crane are reviewed together on the dealer quote.
5. Can I finance a crane bought at auction or from a private seller?
Yes. A lender needs proof of the unit and its price, whatever channel it comes through. Auction timelines are short, so send the listing as soon as you have it.
6. Are crane lease payments tax deductible?
Lease payments are commonly treated as an operating expense in Canada, one reason contractors lease instead of buying outright. Your accountant can confirm how that applies to your structure, and we cover the principle in our article on lease payments and tax.
7. Can I refinance a crane I already own?
Yes. The advance is set against what the unit is worth today, not against what you paid for it. The review runs as it would on a purchase, with the crane in your yard as the asset.
Calculate Your Monthly Payment
Our equipment lease calculator turns a purchase price and a term into an estimated monthly payment.
The arithmetic behind that figure is explained in our guide to how a lease is calculated.
Ready to Finance Your Crane?
Send the dealer quote or the auction listing, with a short note on the work the crane will be doing. Our brokers take the file to the lender network and bring back the crane financing structures that fit, usually within 48 hours. Apply now or call 819-643-9997 to reach one of our representatives directly.